Showing posts with label Personal Finance. Show all posts

02 April 2017

EPF to NPS: Should you jump ship?

Please Share:: Bookmark and Share �� India Equity Research Reports, IPO and Stock News Visit http://indiaer.blogspot.com/ for complete details ��

05 November 2016

Keep-A-Cool-Head-Guide :-) StableInvestor

Please Share:: Bookmark and Share �� India Equity Research Reports, IPO and Stock News Visit http://indiaer.blogspot.com/ for complete details ��

14 June 2015

Income for sunset years : CEO, BankBazaar.com in Business Line

Please Share:: Bookmark and Share

�� India Equity Research Reports, IPO and Stock News Visit http://indiaer.blogspot.com/ for complete details ��

18 January 2015

Is it too early to start investing for my one-year daughter’s marriage? :: Business Line

Please Share:: Bookmark and Share


�� India Equity Research Reports, IPO and Stock News Visit http://indiaer.blogspot.com/ for complete details ��

31 December 2014

Follow these guidelines to become a smart investor in 2015 :: ET

Please Share:: Bookmark and Share
Follow these guidelines to become a smart investor in 2015
�� India Equity Research Reports, IPO and Stock News Visit http://indiaer.blogspot.com/ for complete details ��

28 December 2014

Your Financial Plan :: Business Line

Please Share:: Bookmark and Share

�� India Equity Research Reports, IPO and Stock News Visit http://indiaer.blogspot.com/ for complete details ��
11 November 2014

Ten steps for young couples to help them lead a financially stable life ::ET

Please Share:: Bookmark and Share

�� India Equity Research Reports, IPO and Stock News Visit http://indiaer.blogspot.com/ for complete details ��
03 November 2014

Nivesh Portfolio Tracker | Balanced, Aggressive & Conservative

Please Share:: Bookmark and Share

�� India Equity Research Reports, IPO and Stock News Visit http://indiaer.blogspot.com/ for complete details ��
09 October 2014

8 simple steps to create wealth: Rediff

Please Share:: Bookmark and Share


Wealth creation is a much bigger and broader goal than say 'children's education funding' or 'retirement planning' -- those are sub goals, of course. So every big goal is met by taking a lot of small steps. Here are some of those steps. Not saying these are enough, but this is a good beginning.
1. Look for a good fund manager: The importance of a good fund manager is rarely brought out by the financial press. There is just too much emphasis on costs. HDFC ULIP (when I bought it) had the lowest asset management company (AMC) charges -- of just 0.8 per cent -- however the benefit of low charges was lost by poor fund management skills.
I pay a much higher brokerage than you do (and there are at least three brokerage houses willing to do it free for me). Frankly, as an investor, I could not and need not care about the brokerage rates at all. The quality of advice that I get makes it worth while.
2. Having understood point number 1, make sure that among the good fund managers (I mean the AMC, not the individual) make sure that the costs are reasonable. Too much should not be lost in the premium of good fund management!
3. Start today: This has been said so many times, that it does not need any explanation. Just pick up the phone and call, or go online and invest. NOW.
4. Automate your investing: SIP -- again enough has been said. Do not get distracted by value SIP and variable SIP... and all such concepts. You do not need to tweak it. Pick a fund, pick a date, pick an amount -- and DO it, not today, NOW. This article can wait; your investment cannot.
5. Find areas in your expenditure that can be cut so that you can increase the SIP amount -- even if you can improve by Rs 300 per month, do it. Every drop counts.
6. HDFC and ICICI Mutual Fund allows you to do a rising SIP -- so you could charge with Rs 5000 a month and sign up to increase it by Rs 500 every year. Just see how comfortable it would be to increase. If you are confident, increase by Rs 1000 a year -- your comfort level is necessary.
7. Start doing all this with a friend and open an online account that will help you track your portfolio. Just start tracking your expenses and your wealth accumulation. NOW.
8. See if you have some surplus from time to time. If the answer is yes, your SIP amount needs to be bumped up.


�� India Equity Research Reports, IPO and Stock News Visit http://indiaer.blogspot.com/ for complete details ��

05 October 2014

Four money lessons from Dussehra: Credit Vidya

Please Share:: Bookmark and Share


Dussehra is a festival that marks the defeat of the evil king Ravana by Lord Rama who stands as a symbol of all that is good in humanity according to mythology. In some parts of India it is also celebrated as Vijayadashami or the day when the Goddess Durga defeated the demon king Mahisasura.
In Hindu tradition, Dussehra calls for big celebrations and is regarded to be a time to take a fresh perspective of life and marks the beginning of new things.
As you spruce up for Dussehra puja this year, we have a suggestion for you! How about looking at your finances in a whole new way?
In fact Dussehra has some precious financial lessons that you can implement.
Cast away your bad debt
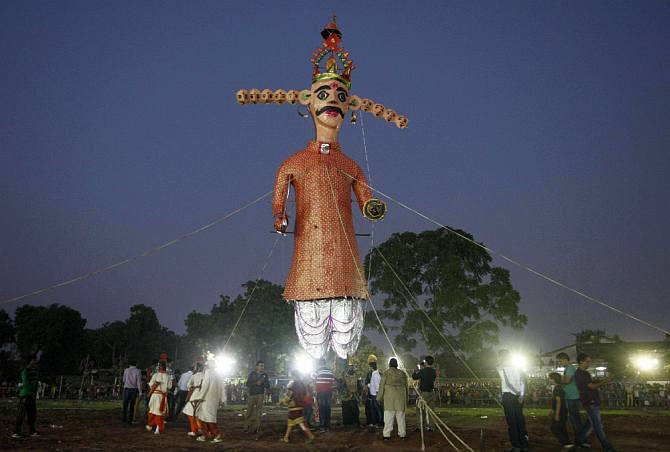
Hindu men prepare to burn an effigy of 10-headed demon king Ravana during Dussehra festival celebrations in the western Indian city of Ahmedabad October 13, 2013. Effigies of the 10-headed Demon King Ravana are burnt on Dussehra, the Hindu festival that commemorates the triumph of Lord Rama over Ravana, marking the victory of good over evil.
Photograph: Amit Dave/Reuters
Dussehra, as we mentioned earlier, is the time when good conquers evil, so if you have too much of credit card debt and are perilously close to reaching your credit limit, focus all your energies towards the repayment of this kind of debt.
This is a debt of the worst sort and can be the real enemy of your financial plan.
Not only is it a high cost debt, as you pay a steep rate of interest on it, it will also impact your credit score negatively over the longer term.
Lead a life of financial self discipline
Lord Rama advocated a life of ‘Dharma’ meaning one has to be upright and responsible in life. The same principles should be made applicable to your finances as well.
If you are an important earning member of your family, you must apply financial discipline in a manner that you take care of your family’s needs not just at present but provide for the future as well.
This means you need to save wisely.
Just like Lord Rama, did not deter in living a life of frugality when it was required of him, you too must learn to live on less than you earn so that you save enough for future needs, like education of your children, health and other emergencies and most importantly have a comfortable and stress free retirement yourself.
Protect your finances
Dussehra is a time when the Hindu faith is renewed in the divine promise, that whenever there is evil prevailing on Earth, a saviour will be born to protect humanity. You too should take a cue from this message and learn to protect your finances.
By protection, we mean, you should have enough life, health and asset insurance.
Mostly, people get so caught up with growing their portfolio that they keep insurance at a minimum. On the contrary, it should be the other way around.
You should first assess the insurance needs of your family and then invest the surplus in other instruments to maximise your gains.
It’s a time for new beginnings
Dussehra also signifies doing away with the old and getting a new lease of life. Apply this principle to your finances as well.
If you do not have a proper financial plan chalked out according to the short term and long term financial goals you have in life, there isn’t a better time to begin!
Dussehra is a time of joy and hope, so make this Dussehra an occasion of immense joy as you vow to approach your finances from a new and fresh perspective.


�� India Equity Research Reports, IPO and Stock News Visit http://indiaer.blogspot.com/ for complete details ��

29 August 2014

When you lose your bank locker key :Business Line

Be prepared to pay for breaking the existing lock and replacing it, besides a fine
Of all routes open to keep your valuables — gold, jewellery, important documents — safe, the locker facility offered by banks is an extremely popular avenue.
But while there is considerable security in stowing away your important stuff in the locker, the solitary key provided to you to open the locker must be kept safe.
Losing it can lead to considerable loss, especially if it lands in the wrong hands.
The problem is especially accentuated if you do not operate your locker for a long time or if your work takes you overseas for prolonged periods.
But what if, even with all your care, you lose that one locker key?
Here are the steps you need to take and the charges that you may incur while addressing the issue with the bank. A typical bank locker has two keys — one is given to you and the other is with the branch manager. Both the keys are needed to open the locker; neither of them alone will suffice.
Your responsibility
The responsibility of safekeeping the key rests solely with you as do the contents in the locker.
The bank will take no responsibility whatsoever for any loss that you may incur on this count. In fact, while signing up for the locker, the documents would clearly state this point.
So, if your bank were a bit lax in checking on customers operating lockers and if the key were to fall into the wrong hands, there is a chance that your locker could be cleaned out.
So, what do you do if you lose your key? First, inform your bank immediately. This way, the bank would be cautious and not allow anyone to operate your locker. You are expected to remember the key or the locker number at least while informing the bank!
You must also always have a written list of things that you hold in the locker, with updates made each time you carry out any operation.
Paying up
After you inform your bank, the next step would be to break open the lock and replace it with a new one. Banks such as Bank of Baroda, Indian Overseas Bank, SBI and City Union charge anywhere between ₹250-and ₹Rs 500 as fine or service charge.
This apart, you will have to bear the charges of breaking and replacing of the lock, complete with two new keys.
The bank normally calls the manufacturer of the locker; breaking the lock will be done in your presence.
The total charges for this activity can cost up to ₹3,000 in the case of most public and private sector banks.
Depending on the size of the locker you hire, the cost of replacing the lock could vary. In case you live overseas and lose your key, try to inform the bank through some local representative in India as soon as possible and arrange for the lock to be replaced, though the procedure for replacing the lock is more complicated.
Easy way out
Short-cuts such as making or using a duplicate key are best avoided in your own interest. If you think you’re being clever in getting a duplicate key made, note that it is a breach of contract. The rule that you should not make copies of the locker key is clearly stated in the agreement while renting out lockers for almost all banks.
The added danger would be that the person who delivers the duplicate keys may make another replica which could be misused.
So, to save yourself all the hassle, keep your locker key under, well, lock and key!

31 March 2014

Start your tax-saving for the new financial year NOW! -Investment Yogi


Don't wait till March next year. The new financial year begins April 1, 2014. Some tax-saving tips based on your age group and tax bracket
Most of us feel tax planning is a boring exercise done every year (or every March) to save tax through various tax saving products. However, like financial planning, tax planning is not the same for everyone.
You need to invest in various products as per factors such as your tax slab, age, risk and so on.
Here is an effort to distinguish tax planning based on your age group and your corresponding tax slabs.
Tax planning for age group 25-35
Most of the youngsters between 25-35 years of age are either in 10 per cent or 20 per cent tax slab.
Section 80C helps save up to Rs 1 lakh.
EPF/NPS should cover up to Rs 25,000 of 80C.
Investment in ELSS should be up to Rs 40,000.
PPF investment can be up to Rs 25,000.
Life insurance premium can be used for deduction up to Rs 10,000.
Under section 80D (mediclaim), tax deduction is allowed up to Rs 15,000. At least Rs 10,000 of this limit should be utilised by opting for individual/floater policy.
There are chances that you are servicing an education loan. Entire interest payment is deductible for exemption from your taxable income.
You would be eligible for RGESS (Rajiv Gandhi Equity Savings Scheme) if you are a first time investor. Under this scheme you can invest up to Rs 50,000 in stocks and save tax up to Rs 2,500 (10 per cent bracket) and Rs 5,000 (20 per cent bracket).
You must have also applied for housing loan. Interest paid can be claimed up to Rs 1,50,000 if you are living in that house.\
Tax planning for age group 25-35
Most of the youngsters between 25-35 years of age are either in 10 per cent or 20 per cent tax slab.
  • Section 80C helps save up to Rs 1 lakh.
  • EPF/NPS should cover up to Rs 25,000 of 80C.
  • Investment in ELSS should be up to Rs 40,000.
  • PPF investment can be up to Rs 25,000.
  • Life insurance premium can be used for deduction up to Rs 10,000.
  • Under section 80D (mediclaim), tax deduction is allowed up to Rs 15,000. At least Rs 10,000 of this limit should be utilised by opting for individual/floater policy.
  • There are chances that you are servicing an education loan. Entire interest payment is deductible for exemption from your taxable income.
  • You would be eligible for RGESS (Rajiv Gandhi Equity Savings Scheme) if you are a first time investor. Under this scheme you can invest up to Rs 50,000 in stocks and save tax up to Rs 2,500 (10 per cent bracket) and Rs 5,000 (20 per cent bracket).
  • You must have also applied for housing loan. Interest paid can be claimed up to Rs 1,50,000 if you are living in that house.


24 February 2014

Little-known tax deductions you might have missed while filing returns :ET

Paying more tax than is due is bad enough. It's worse if you don't even know you have overpaid and are eligible for a refund. Many youngsters are not conversant with tax rules and fail to fully utilise the deductions available to them.

Tax filing portal Taxspanner.com studied last year's returns and found that nearly 51 per cent of salaried taxpayers had not fully used the tax-saving limit under Section 80C. Only one of the four taxpayers had claimed the full deduction for health insurance under Section 80D.

Here are some little-known deductions available to taxpayers. Make sure you claim them when you file your returns this year. If you have already done so, you can file a revised one to claim the deduction you missed.

1. Home loan repayment under Section 80C

If you are paying a hefty home loan EMI, chances are that you will find it difficult to put money in tax-saving options. Take heart. While the interest paid on the home loan is deductible under Section 24b, even the principal portion gets you tax benefits under Section 80C.

This is a godsend for taxpayers, who have not been able to exhaust their Rs 1 lakh saving limit under Section 80C because of the home loan EMI. The deduction for the interest paid on a home loan is capped at Rs 1.5 lakh only in case of a self-occupied house. If you have bought a second house for investment and have rented it out, the entire interest during a given year can be claimed as a deduction. This brings down the effective rate of borrowing for the buyer.

2. 30 per cent standard deduction of rental

If you let out your house, the rent is added to your income and taxed at the normal rate applicable to you. However, there is a 30 per cent standard deduction from this income. So, if you receive a rent of Rs 10,000 per month, the total rent for the year would be Rs 1.2 lakh. Of this, Rs 36,000 would be the standard deduction and you will have to pay tax only on Rs 84,000.

3. Carry forward and adjust capital losses

Certain short-term or long-term capital losses you made during the year can be adjusted against other gains. If you lost money in stocks, equity funds or gold last year, you can set off the loss against short-term capital gains or taxable long-term capital gains from the sale of property, gold or debt funds. If you are unable to adjust the entire loss, you can carry it forward for up to eight financial years.

Suppose you lost Rs 80,000 in stocks and gold funds in 2012-13 and managed to adjust Rs 30,000 against gains from debt funds. You can carry forward the unadjusted loss of Rs 50,000 and keep doing so against other gains till 2020-21. However, you can adjust only short-term losses from stocks and equity funds in this manner. If you have held the stocks and funds for more than one year, the losses cannot be adjusted.
Also, one cannot set off short-term gains from stocks against long-term capital losses from other assets. However, both short-term and long-term losses from other assets, such as gold, property and debt funds, can be adjusted. The taxpayers who earned capital gains from fixed maturity plans (FMPs) and debt funds will find this particularly useful.

27 September 2013

Invest in equity funds only for the long term:: Business Line

I am a 52-year-old government employee and I wish to invest around Rs 4 lakh in a safe avenue. I also plan to invest Rs 10,000 per month in mutual funds through the SIP (systematic investment plan) route.
Could you please guide me to safe and guaranteed ventures so that I can spend my retired life with financial security?
K. Saraswathi
The only ‘safe’ avenue available for investors is the bank fixed deposit or other government-promoted schemes such as the NSC or the PPF. Any other investment that is even remotely market-linked is subject to volatility and fluctuation in returns. So, park the amount in a fixed deposit or the NSC.
Again, with respect to your SIP investments, there is no fund that can give you assured or guaranteed returns.
You can consider investing regularly in the NSC or PPF so that you accumulate a reasonable corpus for your retirement.
But if you can take a little bit more risk, you can consider balanced funds. Schemes such as Tata Balanced, ICICI Pru Balanced and Birla Sun Life 95 have good long-term track records. Split the amount equally among these three funds.
Monitor their performance regularly and book profits in case of substantial rallies.
Once you accumulate a corpus with these funds, then closer to retirement, exit these funds. The amount accumulated can be parked in a fixed deposit that gives you a monthly interest payout.
The interest amount can be invested in a monthly income plan. Some plans with a proven track record are HDFC MIP Long Term, Reliance MIP and Birla Sun Life MIP.

17 September 2013

10 ways in which you can negotiate your salary :: ET

If you didn't bag the best compensation in the market when you switched jobs, don't worry. The best of professionals come up short when it comes to discussing salary with a new employer.

Here are some of the common mistakes you can avoid while discussing your salary with a potential employer.

1) Accept initial offer and lose Rs 1 crore

Always, always, always negotiate. Women and first-time job seekers are more prone to accepting the opening offer without questioning it. A 10% salary difference in the first job with a CTC of Rs 4 lakh represents a lifetime loss of over Rs 1 crore, assuming a 15% annual hike over a 40-year career.

So, politely restate your case and provide justification for a revised offer. In over 95% of the cases, the employer has not made his best offer right away and is expecting you to negotiate upwards. As a ballpark, ask for a 10% increase.

2) Do your homework on position & firm

Thoroughly research the market and the firm. In negotiations, as in war, the better prepared side wins. Never approach a new employer without finding out the standard market salary for the position offered based on your experience and qualification.

Start with online research, and then talk to professionals and recruitment consultants. You can also speak to people in the company to have an idea about the latest state of its business, operations and the compensation structure. Use this data to justify your stand.

11 September 2013

How to choose tax-free bonds :: Business Line

Buy a bond with a maturity closest to your investment horizon.
The current bond offering from Rural Electrification Corporation (REC) has prompted us to revisit the subject of tax-free bonds. Rather than look at whether REC bonds are attractive, our objective here is to show you how to choose tax-free bonds to align your investments with your life goals. We will use the features of the REC bonds to discuss the factors that you need to consider when you invest in tax-free bonds.

WHY TAX-FREE BONDS?

Your investment portfolio should necessarily have bonds. Retail bond products have fixed cash flows and finite maturity. This means you will know at the time of investment how much interest you will receive every year and when you will get back your initial capital. You should, for instance, invest in a 10-year bond if you need to fund your child’s college tuition fees 10 years hence. And if expected bond returns are lower than your required return, you should invest a proportion of your capital in equity.
In other words, you have to always invest in bonds. The issue is that interest income is taxed at your marginal tax rate. So, if you receive 9 per cent interest on your fixed deposits, your actual post-tax return at 30 per cent tax rate is 6.3 per cent. And this return will only get lower if the government increases the marginal tax rate for high-income earners!
So, what should you do? Your objective is to ensure that most, if not all, of your bond investments earn tax-free interest. This leaves you with two choices at present. You either have to invest in securities that can fetch you exemption under Section 80 of Income-tax Act for Rs 1 lakh every year. Or you have to buy tax-free bonds. And since Section 80 has an upper investment limit, you have to consider tax-free bonds for your bond portfolio.
The question is: Are you investing excess money at your disposal (discretionary wealth) or are you investing to achieve an objective? If it is the latter, you should buy a bond with maturity closest to your investment horizon. Suppose your daughter is scheduled to enter college 11 years hence, you should buy the 10-year tax-free bond, even if the 15-year bond is attractive!
But what if your investment horizon is 20 years or you are investing your discretionary wealth? You should use the break-even rule. That is, to make a meaningful comparison between, say, the 15-year and the 20-year bond, you will have to assume that all cash flows from the 15-year bond will be reinvested for additional 5 years. The rule is : Invest in the 15-year bond if the break-even rate appears lower than the expected 5-year deposit rate 15 years from now; break-even rate is the rate which makes you indifferent between investing in the 20-year bond, and buying the 15-year bond and reinvesting the proceeds in a 5-year bond.

BREAK-EVEN RULE

Based on the break-even rule, the 15-year REC tax-free bond appears attractive compared to the 20-year bond, if you expect the 5-year rate 15 years from now to be more than 5.9 per cent post-tax or 8.5 per cent pre-tax (at 30 per cent marginal tax rate). But the 20-year bond becomes attractive if you expect the tax rate to increase!
You do not have to forecast interest rates to apply the break-even rule. You have to intuitively sense whether the rate in the future will be higher or lower based on the current rate levels. The break-even rule helps you to choose bonds systematically. Importantly, the rule forces you to consider reinvestment risk instead of simply buying a bond that offers you higher interest rate today. You can use the break-even rule for your investments in bank fixed deposits as well.

24 August 2013

When and how can you withdraw from your EPF? By BankBazaar in ET

Almost all salaried people contribute a certain percentage of their salary towards their Employee Provident Fund (EPF) account every month. While most of us know that EPF is an effective tool that helps generate a corpus for life post retirement, many of us are unaware that you can make a withdrawal from your EPF account for urgent cash requirements.

However, an EPF account cannot be treated like any other saving bank account implying that there are certain specified criteria under which withdrawal is permitted from an EPF account. An individual needs to furnish all relevant documents and satisfy the necessary requirements in order to be eligible for premature withdrawal of EPF.

Here are the categories and other details with respect to premature withdrawal from EPF.


ReasonRequirementAmount allowedNo. of times permitted
Education or marriage


> The employee should have completed at least 7 years of employment or service.

> Withdrawal allowed for self, sibling(s) or children's marriage.

> 
Withdrawal permitted for self or children's education only.

> Proof of the education or wedding required to be submitted, such as a valid copy or a bonafide certificate of the payable fees or the wedding invitation.

> In case of education, the individual needs to apply in Form 31 through his/her employer.
50% of the total corpus amount till date


Permitted thrice only during a person's total service tenure


Medical treatment


> Withdrawal permitted for medical treatment of self, spouse, parents and children.

> There is no restriction regarding the number of years of service.

> The proof of hospitalization for a month or more along with an approved leave certificate from the employer for the corresponding period needs to be produced.

> The member needs to obtain and deposit a certificate from the employer or ESI stating that ESI facility is not accessible or available to him/her.

> A certified proof or document of the disease should be submitted in Form 31 while applying for withdrawal.
6 times the monthly salary of an individual or the total corpus amount, whichever is lesser


Anytime


Purchase of a plot


> Should have completed at least 5 years of service.

> The plot or property should be registered in the person's or his/her spouse's name or should be owned jointly.

> The plot should not be entangled in any legal issues and the agreement registered under the Indian Registration Act with the Flat Promoter needs to be submitted along with the application form.
Up to 24 times the salary of the individual


Once during entire service tenure


Construction or purchase of a flat, house or plot> Should have completed at least 5 years of service.

> The house should be registered in the person's or his/her spouse's name or should be owned jointly.
36 times the monthly salary of the individualOnce during entire service tenure
Repayment of Home Loan> Should have completed at least 10 years of employment.

> The house should be registered in the person's or his/her spouse's name or should be owned jointly.
36 times the monthly salary of the individualOnce during entire service tenure
Alteration or Renovation of house> Should have completed at least 5 years of service.

> The house should be registered in the person's or his/her spouse's name or should be owned jointly.
Up to 12 times the individual's monthly salaryOnce during entire service tenure
Pre-retirement> The individual must be at least 54 years old.90% of the total corpus amountOnce during entire service tenure


07 June 2013

Invest early to build a healthy corpus :: Business Line

I am 55, and work in a PSU. I retire at 60 with no pension benefits. I have generally invested in all the ‘conservative’ financial instruments such as VPF, PPF, bank fixed deposits, NSC, gold and insurance policies of LIC. I have also purchased a flat. I keep reading that investing in mutual funds is the only way to beat inflation and that it will add significantly to the retirement kitty.
I would like to invest Rs 15,000-20,000 every month for the next five years. Considering my profile, can you suggest 4-5 mutual funds I can invest in? These investments should not be too risky. I am looking at returns of around 15 per cent. Once I retire should I move to MIPs?
C.A. Rao
As you yourself have stated, most of your investments are in traditional products — mostly debt oriented schemes.
You should have started investments in mutual funds a little earlier, say, at 45 or 50. That would have enabled your investments to grow at a fair pace to give you a healthy corpus.
Investments in equity or equity mutual funds give you a better chance at beating inflation. But over the last 4-5 years, inflation itself has been in double digits and most diversified equity funds failed to even match this rate, let alone beat it.
Of course, if you take a 10-year horizon, then diversified equity funds have handsomely beaten inflation.
That is why we insist on longer term investments of 10-15 years for you to have meaningful capital appreciation.
So, with your low risk appetite and investment horizon of five years, achieving 15 per cent annual returns may be quite challenging. You will do well to temper it down to 10 per cent.
Split Rs 20,000 as follows: invest Rs 5,000 each in Franklin India Bluechip, HDFC Equity and Quantum Long Term Equity. Park Rs 3,000 in HDFC Balanced and Rs 2,000 in IDFC Premier Equity.
The portfolio is mainly large-cap focused, which is relatively less risky. We have included a mid-cap fund to perk up returns.
At the end of five years, reduce exposure to equity funds substantially or exit them altogether if you have little penchant for risk. If there is any abnormal rally in the market, book profits and move the proceeds to safer avenues.
Move to safe debt avenues or MIPs after you turn 60 and opt for monthly or quarterly payouts, especially as you have no pension benefits, post-retirement. Some of the MIPs you can consider are: HDFC MIP Long Term, Canara Robeco MIP and Reliance MIP.
***I am 47 years old and have been investing Rs 30,000 every month for the past one year under SIP mode in the following funds: HDFC Mid Cap Opportunities; ICICI Pru Focused Bluechip; UTI Opportunities; Reliance Banking; IDFC Premier Equity and ICICI Pru Discovery.
I am investing this for developing a corpus for my old age. Are my investments on the right track?
Subramanyan
It is nice to note that you have been investing systematically for your retirement. Having said that, there seems to be no specific focus to your portfolio and choices appear quite random.
Also, there are too many mid-cap funds in your portfolio and a banking fund as well. For the record, Reliance Banking is a fund with an excellent track record over the long-term. But sector funds require timing for entry and exit. So, stay away from such funds for long-term portfolio building purposes. Also, we assume that you have made sufficient allocation to other investment avenues such as debt (FDs, RDs, PPF, etc), gold and real-estate.
You have not stated the allocation to each scheme. So consider splitting Rs 30,000 as follows: invest Rs 6,000 each in ICICI Pru Focussed Bluechip Equity, UTI Opportunities and Quantum Long Term Equity. Invest Rs 4,500 each in IDFC Premier Equity and HDFC Midcap Opportunities.
Exit ICICI Pru Discovery, even though it has a proven track record as you already have two mid-cap funds in your portfolio and another scheme from the ICICI stable.
Your portfolio now has a blend of large-, multi- and mid-cap funds, making it a balanced portfolio.
Park the balance Rs 3,000 in Birla Sun Life Dynamic Bond Fund. If you already have sufficient debt investments, invest Rs 3,000 in Reliance Gold Savings. Review your portfolio once every year and take corrective action to rebalance. Also, try to weed out underperformers.
Move proceeds from equity funds to safer debt avenues if you reach your target corpus ahead of the anticipated time.